Showing posts with label drivers. Show all posts

Monday, March 3, 2014

Mitsubishi high-tech dashboard for distracted drivers

Mitsubishi high-tech dashboard for distracted drivers
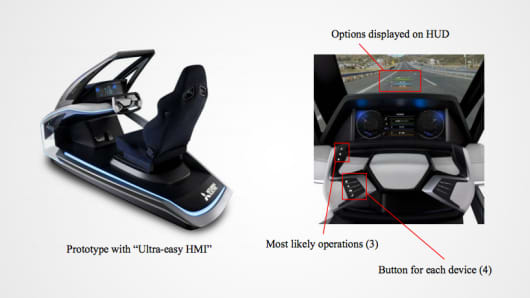
Mitsubishi has a high-tech remedies for distracted drivers: a minimalist design dashboard and console, which works by predicting what instruments have a driver at any given time, according to an article in quartz.

Conventional cars are crammed with buttons and controls for different tasks and drivers often divide their attention sound systems or checking email and social media further by adaptation. Mitsubishi's new system, which the company hopes to have in cars by 2018 is largely free opt instead for two consoles, each with just a few button controls. The functions of these buttons change: the system uses data - able to predict speed, road conditions, history and weather - what a driver is need to or want to. Voice-activated controls serve as a backup, just in case.

Thursday, February 14, 2013

'Good drivers' pay more for insurance, study often

'Good drivers' pay more for insurance, study often

By Kraut white tree, today registered users
If you believe that you display, good drivers will receive the best insurance rates. But a new study shows auto insurance companies often good drivers require higher premiums than those who caused an accident recently. And it seems from this research that the safe driver, the more numbers often lower income.

How could this happen?

The Consumer Federation of America (CFA), which conducted the study, says that this reflects a common practice in the insurance industry with factors such as education and profession, interest-rate risk.

A CFA survey in 2012 showed that two-thirds of Americans believed taking into account these factors, but driving story was unfair.

Stephen Brobeck, Executive Director of CFA, this is called a "discriminatory practice", which auslost-prices for low- and moderate-income drivers.

The industry rejects any notion that it will be disadvantaged in any way.

"The policies we offer fair in all respects, are," said Michael Barry, Vice President media relations at the insurance information Institute.

How to measure CFA marketplace
The CFA guidelines for two hypothetical customers price: high school receptionist and Manager. Both women were 30 years old, driven for 10 years had lived on the same street in the same zip code with medium income.

But there were important differences.

The reception is single, rents an apartment. She was never an accident or moving violation, but she was without insurance coverage for 45 days.

The Executive Branch is married to homeowners with a master's degree. Your car insurance policy has never expire. But she had an accident on errors with $800 damage within the last three years.

CFA scientists visited sites of the five largest U.S. car insurance - state farm, Allstate, GEICO, farmers and progressive - in search of the minimum liability coverage required by this State. This was for both women in 12 cities.

As a result, two-thirds of the 60 citations were for the Executive Branch (which had an accident) as for the receptionist (had), less often by at least 25 percent.

The insurance information Institute asks whether the test was fair, because the receptionist had a break in insurance and this could be seen as a risk factor. The Consumer Federation of America says the receptionist had no car for 45 days and therefore needed no insurance. Questions that make your car more risky, they?

Why is this happening?
Insurance companies hold a variety of factors determine the risk they represent and the price they should charge if you apply for an auto policy. All agree that your age, gender, type of vehicle and driving history can help to predict the probability that you will have an accident.

However, insurance underwriters should your education, career, or in some cases, your credit score? What have these social and economic factors, to do with your ability, a safe driver?

"These factors was found, that possibilities be insurance statistically solid risk assessment," said Michael Barry, Vice President media relations at the insurance information Institute. "And before they are ever used, these rating criteria are tested, State insurance regulators who have allowed them."

CFA says it's not fair for someone who get a better rate, simply because they have more education and more income.

"Our concern is that these factors are not proved, There is no logical reason to explain why they should work, '' said Robert Hunter, CFAs Director of insurance and former Texas Insurance Commissioner. "The insurance companies say there is a link, and that's all what you need."

Some insurance companies consider your credit scores now, if you set your premiums. Not too good with Washington State Insurance Commissioner Mike Kreidler, sit, which calls the practice "blatantly unfair" way to assess the risk.

"I think it's terrible," me Kreidler. "Do you use a credit score in this economy? You have people who have no fault ultimately with less quality credit and yet drivers are still responsible. You should not pay more for auto insurance because of that."

Not in the Sunshine state
The California Insurance Department decides what reviews are factors of car insurers car pricing. Education, not to look at work and credit scores.

"We want criteria that have a relationship to the risk of loss," said Joel Laucher, California Deputy Insurance Commissioner for tariff regulation.

"You want something, that is fair and quite intuitive, so that people understand why there was a difference in price." "It should be something the driver can control and realize, how they change their behavior to improve their rate can be."

Massachusetts restricts the use of socio-economic factors for private car insurance.

"A determination was made that to drive insurance an individual car must listen more closely", said Massachusetts Insurance Commissioner Joe Murphy.

The bottom line
There are many insurance companies for your company in the competition. Prices are very different.

A good start is your insurance Department Web site. Find a comparison chart that lists the prices in your area for various hypothetical clients. It is an easy way to see how the different insurance companies to compare, and where you go, would like to receive an offer.

(Find a link to your insurance Department at: National Association of Insurance Commissioners.)

Receive offers from an independent agent who represents several companies or go online and do it yourself sites such as InsWeb, NetQuote, InsuranceHotline, InsuranceQuotes, financial response. Expect no immediate offer from these pages. In most cases you won't find agents be contacted for your company.

Friday, September 28, 2012

Mississippi leads way in drivers ' misery index'

By Paul A. Eisenstein, the Detroit Bureau
It is to feel just miserable, if it wide the tank with fuel prices again on a fast rise over time to fill parts of the country. And car insurance costs have become fast, also will.

But vary how much you can pay heavily depending on where you live. A gallon of regular unleaded, that cost is $3.16 in South Carolina this week more in Illinois goes for a dollar, according to the latest tracking information.

Combining gas and insurance and drivers in some States can costs index as much as $2,000 more than their cohorts driving in other parts of the country, according to the new automotive misery.

Measured another way, these personal transport costs alone ranging from less than 5 percent of the income of the average motorist after more than 11 percent, according to research by CarInsurance.com.

Gas and insurance damage in New Hampshire, according to the index, on average $2.932, at least a year, or 4.4 percent of the typical household income. Alaska, Connecticut, Colorado, and Washington rounded the top five, with their misery index at or below 5 percent.

At the other end of the scale, with misery is index of 11.6 percent. Drivers in that State not only are some of the highest insurance and gas costs-at $4.277 every - but have lower income to cover the costs.

The insurance costs alone a year ranging from Maine in an average $889 $2.589 in Louisiana. $1.479 Was found, the national average, CarInsurance.com.

The site even more looked at insurance and found that they vary down to postcode level. In a part of the Bayou State, drivers are only $1.874 have to shell out. Elsewhere however that almost to $3.530 doubled.

A variety of factors influence the gas and insurance costs. States rather closer to ports and refineries and usually cheaper fuel benefit Gulf and East Coast. Generally higher costs in the Midwest have spiked in recent months due to the pipeline and refinery problems.

As for insurance, prices can be affected, whether a State is more urban or rural and as many miles drivers tend to drive. Drivers tend to be in Wyoming, 44th on the misery index, more than 20,000 miles per year, compared to the national average of 14.133 pm.

Missippi, that the misery index exceeded, is a rural state, but "People drive many,", said CarInsurance editor of Toups. "It has also the highest percentage of uninsured motorists, car insurance so much power more expensive."

Friday, September 14, 2012

Worst drivers in America? Washington, D.C., takes the honor

Worst drivers in America? Washington, D.C., takes the honor

AP

Not only are the drivers bad, there's too much traffic. Motorists slog through the commute around Washington, D.C.

For those of us who live in and/or drive through major metropolitan areas, having to keep a watchful eye out for the antics of inattentive or even reckless drivers is a necessary part of our daily routine. You may think you’ve got it bad, but according to the eighth annual “America’s Best Drivers Report” issued by Allstate Insurance in Northbrook, Ill., Washington D.C. can again lay claim to having the absolute worst motorists in the nation.

Allstate studied the auto insurance claims frequency of America’s 200 largest cities and found that residents of our nation’s capital were found to get into collisions on average once every 4.7 years. This means they’re a whopping 112.1 percent more likely to be party to an accident than the typical driver in the U.S., who wrecks his or her car once every 10 years.

Taken on a statewide basis, California would seem to have the worst drivers overall, placing five cities among the top 25, including Glendale (5), San Francisco (10), Los Angeles (14), Fullerton (16) and Torrence (22). New Jersey came in a close second with four cities among the top 25, with Florida and Virginia tied for third with three cities each.

And, no, New York City didn’t even make the top 10 in Allstate’s 2012 list, though it still ranked at number 20, with residents being 41.1 percent more likely than the average motorist to get into an accident.

Meanwhile, the safest drivers can be found trolling the streets of Sioux Falls, South Dakota, where the average motorist experiences a collision only once every 13.8 years, which is 27.6 percent less likely than the national average. Other top-five safest cities include (in order): Boise, Idaho; Fort Collins, Colo.; Madison, Wis., and Lincoln, Neb.

Among larger metro areas, the safest cities include: Tuscon, Ariz., (13); Milwaukee, Wis., (15); and Kansas City, Mo., (16).

"It is vital for us to educate American drivers about safe driving behaviors they can practice on the road that will help make our roadways safer,” says Dave Prendergast, Allstate’s field senior vice-president. “Minimizing distractions, obeying traffic laws, and using your car’s safety features like turn signals and headlights, are all ways to be safer, no matter where you drive.”

Here is Allstate’s full list of the 25 cities having the worst drivers, with each citation noting the likelihood a motorist living there is to be involved in a crash, relative to the national average:

Washington, DC: 112.1% greater-than-average accident frequencyBaltimore, MD: 87.9%Providence, RI: 80.9%Hialeah, FL: 77.6%Glendale, CA: 77.5%Philadelphia, PA: 64.1%Alexandria, VA: 62.6%Newark, NJ: 59.4%Miami, FL: 58.4%San Francisco, CA: 54.6%Jersey City, NJ: 53.9%Arlington, VA: 53.0%Tampa, FL: 50.2%Los Angeles, CA: 48.5%Paterson, NJ: 46.9%Fullerton, CA: 42.7%Garland, TX: 41.6%Elizabeth, NJ: 41.5%Bridgeport, CT: 41.2%New York, NY: 41.1%New Haven, CT: 37.5%Torrance, CA: 36.7%Norfolk, VA: 36.3%Yonkers, NY: 36.2%Arlington TX: 35.4%

The fine print: the 2012 Allstate America’s Best Driver’s Report is based on an actuarial analysis of company claim data among the nation’s 200 largest cities. Property damage claims were analyzed over a two-year period (from January 2009 to December 2010) to ensure the findings would not be impacted by external influences such as weather or road construction. A weighted average of the two-year numbers determined the annual percentages. The report defines an auto crash as any collision resulting in a property damage claim.

Saturday, July 28, 2012

Drivers can now benefit from the application of OnStar

By Robert E. Calem, TechNewsDaily
OnStar subscribers have long to look with the technology of the company from a distance, to lock or unlock and start or stop their vehicles. As of Tuesday, you can also use to make a profit.

The partnership between GM OnStar and RelayRides, a peer-to-peer car sharing service, is now possible thanks to an exclusive new technology exchange people their car for any period from one hour up to a week to others rent, to find it online or through a Smartphone app.

RelayRides can now find tenant members, unlock and lock OnStar-equipped vehicles, they have paid to rent, direct access to the vehicle within the service app or through a text message reply. And owners OnStar-equipped vehicles can now safely hide your car keys inside their vehicles and tenants personally go with their other activities, instead of car keys passed - as owner not OnStar equipped vehicles have to do still.

Could owner members earn much money from their rental vehicle through the service and the risks are low, because RelayRides offers liability, collision and comprehensive insurance for the rental period. Owners are subject to a $1 million policy, tenants will receive a $300,000-normal car insurance is not involved in politics and users.

A current search the RelayRides marketplace for cars available in the Hoboken, n.j., turned a number of vehicles, which ranged in price from $6 to $50 per hour or $45 to almost $1,000 per day. ("Ravi included the Honda," a 2007 civic, which rents for $6 per hour or $45 per day and "Logan's BMW," a 2008 3 convertible, which for $50 per hour or $250 per day rented.)

RelayRides cars are available at locations in the United States, but in some of these areas, it is not the only peer-to-peer car sharing service. Competitive operations Getaround (in San Francisco, San Diego, Austin, Texas and Portland, Oregon/United States) include, Wheelz (serves the communities for four universities in California: Stanford, UC Berkeley, UCLA and USC). Getaround, in particular offers a technology option enabled, by the Alliance of similar to OnStar RelayRides: the Getaround car kit brings in each vehicle and combines GPS, Wi-Fi and Keyless remote technology.

Copyright 2012 TechNewsDaily, a TechMediaNetwork company. All rights reserved. This material cannot be published, sent, rewritten or redistributed.

Saturday, June 9, 2012

Buckle up: The most dangerous states for drivers

Buckle up: The most dangerous states for drivers

In 2007, Montana had 11.1 drunken driving auto deaths per 100,000 residents, the highest rate in the U.S. that year.

By Michael B. Sauter, 24/7 Wall St.
According to the U.S. Centers for Disease Control, more Americans aged 5–34 die from motor vehicle crashes than from any other single cause. Despite this disturbing fact, a study released this week shows that states where fatalities caused by car accidents are very high are also states that are doing the least to prevent those accidents.

24/7 Wall St.: America's most corrupt states

The Trust for America’s Health, a nonprofit disease prevention group, released a report earlier this month on various causes of injuries and deaths in the United States. Included in that report is a by-state analysis of CDC data on auto fatalities, the costs arising from all fatalities and the policies states use to prevent car crashes. 24/7 Wall St. reviewed the 10 states that had the highest rates of auto fatalities.

Deaths caused by motor vehicle accidents in the U.S. vary widely. Twelve states averaged less than 10 deaths per 100,000 people per year during 2007 to 2009. Massachusetts had the lowest average yearly rate in the country of just 5.5 per 100,000 people. On the other end of the spectrum, 14 states had at least three times as many deaths per 100,000 people. Mississippi had close to five times that rate.

A CDC report identified the estimated lifetime costs incurred by the states as the result of auto fatalities in a single year, including medical expenses and lost economic productivity. These two costs exceeded $170 billion in the U.S. in 2005, the most recent year data are available.

With such high costs and, more importantly, loss of life, the question is whether there is anything states can do to prevent car accidents. The Trust for America’s Health found that nothing works better to prevent traffic deaths than seat belt use. According to a report released by the National Highway Traffic and Safety Administration, six of the 10 states with the lowest seat belt usage rates also had the highest average auto fatality rates between 2007 and 2009.

The Trust for America’s Health report also identified four key policies labeled by the CDC as useful in improving traffic safety. The four include having a primary seat belt law (which allows police to stop and ticket unbuckled drivers without any other cause), a mandatory ignition interlock for all convicted drunken drivers, a mandatory motorcycle helmet law and requiring booster seats for children 8 years old and younger.

24/7 Wall St.: America's favorite beers

Despite the massive financial burden auto accidents place on states each year, it appears many still fail to enact the kinds of basic safety laws that are believed to be instrumental in reducing auto accident deaths. In fact, it appears that the states with the highest rates of auto fatalities lack some of those key policies. Of the 15 states with one or none of these policies in place, seven were among those with the highest fatality rates.

24/7 Wall St. ranked all 50 U.S. states based on the highest yearly average automobile deaths per 100,000 people from 2007 to 2009. 24/7 Wall St. also calculated the total costs incurred by each state for these deaths using the CDC’s WISQAR report, which was for 2005. While the average auto mortality rate and the cost estimates are from different time periods, each set of data is the most recently available, and the data were analyzed to determine the approximate actual costs of traffic deaths.

1. Mississippi

Average auto fatalities per 100,000: 26.7 (the highest) Auto fatalities/year: 784 (19th most) Lifetime medical costs due to one-year auto accidents: $7,158,007 (19th highest) Lifetime work-loss costs due to one-year auto accidents: $823,487,544 (17th highest) Percent commuters traveling 30 minutes or more: 30.83 percent (25th lowest)
Mississippi had the highest motor vehicle-related death rate in the country between 2007 and 2009. An average of 784 state residents die each year in accidents, a rate of 26.7 fatalities per 100,000 people. According to the most recent CDC data, a single year of auto deaths in the state is estimated to cost more than $820 million in lost productivity. The state has a primary seat belt law, and motorcycle helmets are mandatory, but it does not require ignition locks for convicted drunken drivers, and is one of 18 states that does not require booster seats for children 8 or younger.

2. Montana

Average auto fatalities per 100,000: 23.3 (second highest) Auto fatalities/year: 225 (11th least) Lifetime medical costs due to one-year auto accidents: $1,831,676 (12th lowest) Lifetime work-loss costs due to one-year auto accidents: $195,289,017 (11th lowest) Percent commuters traveling 30 minutes or more: 18.05 percent (fourth lowest)
With an auto injury fatality annual average of 23.3 per 100,000 residents in the period between 2007 and 2009, Montana has the second highest rate on the list. The problem may be due in part to drunken driving. In 2007, Montana had 11.1 drunken driving auto deaths per 100,000 residents, the highest rate for that year. Montana has done little to respond to these figures. The state has not adopted any of the four auto-safety policies that were identified as critical by the CDC. Despite the high fatality rate, the medical costs and work-loss costs associated with them rank in the bottom 15.

3. Alabama

Average auto fatalities per 100,000: 21.7 (tied third highest) Auto fatalities/year: 1,014 (11th most) Lifetime medical costs due to one-year auto accidents: $8,254,510 (15th highest) Lifetime work-loss costs due to one-year auto accidents: $964,444,444 (13th highest) Percent commuters traveling 30 minutes or more: 32.85 percent (19th highest)
Alabama’s auto fatalities rate of 21.7 per 100,000 residents is tied for third highest. Single-year fatalities cost an estimated $8.2 million in medical costs, more than all but 14 states. Such an elevated rate of auto fatalities is surprising when contrasted with the state’s 91.4 percent seat belt usage rate. The high rate of auto injury deaths may be attributable in part to the lack of several key safety laws. Alabama does not mandate ignition interlocks for all convicted drunken drivers or requires booster seats for children under 8 years of age.

24/7 Wall St.: The most (and least) peaceful states

4. Wyoming

Average auto fatalities per 100,000: 21.7 (tied third highest) Auto fatalities/year: 116 (seventh least) Lifetime medical costs due to one-year auto accidents: $947,934 (fourth lowest) Lifetime work-loss costs due to one-year auto accidents: $107,859,504 (seventh lowest) Percent commuters traveling 30 minutes or more: 16.43 percent (third lowest)
Wyoming had an average of 21.7 auto injury fatalities per 100,000 people during each year between 2007 and 2009. Though the state has the smallest population in the country, with just 533,556 residents, its lifetime work-loss costs due to auto fatalities are estimated to exceed $100 million in a single year. Only about 16 percent of Wyoming’s workers commute more than 30 minutes per day, the third-lowest rate in the U.S. Despite the high fatality rate, Wyoming has not been proactive in addressing the issue legally. Presently, Wyoming does not have a primary seat belt law, nor a law mandating ignition interlocks for all convicted drunken drivers — only those who register a blood alcohol content of .15 receive the interlock. Additionally, attempts to ban texting in the state have failed in each of the past two years.

5. Arkansas

Average auto fatalities per 100,000: 21.6 Auto fatalities/year: 619 (22nd most) Lifetime medical costs due to one-year auto accidents: $4,775,033 (24th lowest) Lifetime work-loss costs due to one-year auto accidents: $617,945,384 (24th highest) Percent commuters traveling 30 minutes or more: 26.02 percent (13th lowest)
Arkansas has the fifth-highest rate of auto injury fatalities. Between 2007 and 2009, the state averaged 21.6 fatalities per 100,000 residents per year. Arkansas has implemented a comprehensive highway safety plan for 2012. In the plan, the Highway Safety Office set specific goals for reducing DWI deaths, increasing seat belt usage, and slowing drivers down. The HSO hopes to accomplish these goals by bolstering training programs for law enforcement officials and educating the people through a series of high-visibility campaigns.

Friday, April 20, 2012

Drivers grumble, naturally, over NYC's new cabs

Drivers grumble, naturally, over NYC's new cabs

Nissan has unveiled New York City's "Taxi of Tomorrow" - featuring sliding doors, anitbacterial seats and outlets to charge your phone. Take a ride through taxi cab history, including the original Electrobat, horse-drawn cabs and the iconic Checker. 

By Paul A. Eisenstein, msnbc.com contributor

Like most New York taxi drivers, Hakan Karakas has a ready opinion on everything – especially when you ask him about the “Taxi of Tomorrow.”


“It’s like the communists have taken over,” he laments.  “This is a free market, and I should be able to choose what I drive.”


But the fact is Hakkan and the rest of the Big Apple’s independent and fleet taxi owners won’t have a choice. This week they’re getting a first look at the vehicles that will replace the aging Ford Crown Victoria sedans that have long served as the majority of New York’s yellow cabs.


Slideshow: A brief history of NYC taxi cabs


The winner of a city-sponsored shoot-out for the contract was Nissan, which will begin supplying a specially modified version of its NV200 commercial van to New York hacks next year. By sometime in 2018, New York taxi regulators expect the Taxi of Tomorrow to replace all 13,000 vehicles plying the city's concrete canyons today.


At a price of $29,700 the Nissan yellow cab won’t come cheap, prompting some grumbling by operators.  But at a news conference this week to reveal the final design, Mayor Michael Bloomberg insisted the new model “was designed for those who matter most: the passengers and the hard-working drivers.”


Among the many advantages: Nissan conducted extensive safety testing with all the taxi hardware – including the glass partition between driver and passengers – in place.  It has developed special airbag systems to further enhance safety.


NYC Drivers grumbleStan Honda / AFP - Getty Images


Marvin Wasserman (R) and Jean Ryan (L) of the Taxis for All campaign protest outside the unveiling of the Nissan NV200.


The NV200 will be powered by a modest and reasonably fuel-efficient four-cylinder engine, rather than the big V-8 in the Crown Vic. That might frustrate drivers jockeying for position on crowded streets but will save plenty of money on fuel considering the time the typical yellow cab spends stuck in midtown traffic or crawling along the Brooklyn-Queens Expressway on the way to LaGuardia Airport.


The new model also will be “the most comfortable taxi ever to hit our streets,” said Bloomberg, pointing to amenities including better interior lighting, USB and 12-volt power ports for cellphones and iPads, and even carbon ceiling covers and anti-microbial floor mats to keep things cleaner and minimize odors.


The Taxi of Tomorrow will offer 10 more inches of legroom than current cabs and there will be no hump down the middle of the floor that makes it so unpleasant, today, to get stuck with the center seat.


Spencer Platt / Getty Images


Nissan CEO Carlos Ghosn, left, and New York Mayor Michael Bloomberg enjoy the roomy back seat of the new taxi prototype.


“Sounds great to me,” said Robin Milstein, a Manhattan bank clerk, as she struggled to exit gracefully from an old Crown Victoria on her way home to city's SoHo neighborhood.  “It’s such a pain getting in and out, especially when you get one of the smaller cabs they have these days.”


Not everyone is pleased.  A small group of protestors gathered outside the news conference holding hand-lettered signs criticizing Nissan for not making the NV200 handicap accessible. Nissan says it has designed the new taxi to include a rear ramp for wheelchairs, though it is unclear whether that will be a requirement or just one of the options for taxi owners to choose from.


The debut of the Taxi of Tomorrow coincides with the opening of the 2012 New York Auto Show.  For many city residents, it may be as close as they get to an automobile in day-to-day life. The Big Apple –- and Manhattan, in particular -- has the lowest per capita car ownership rate in the country. The yellow cab is the automobile for people who have no interest in cars.


Since the days when motorized hacks took over from horse-drawn carriages, the yellow cab has become an integral part of the city fabric, says New York-based writer Kate McLeod, and not just for locals.


“For many people who come to New York, riding in a yellow cab is a part of their to-do list,” she says.


That experience will be just a bit different – and notably more sightseer-friendly – starting in 2013.

Wednesday, January 25, 2012

Drivers again faulted over Toyota acceleration

A two-year study looking for possible causes behind Toyota’s rash of unintended acceleration issues has put primary blame on driver error — but the review by the National Academy of Sciences also cautioned that some problems may have been caused by inadvertent interactions involving vehicle electronics — an issue frequently cited by the automaker’s critics.


Though there was no hard evidence of specific electronic defects, the 139-page report cautioned that “the absence of evidence is not the evidence of absence.” Warning electronic faults may be “untraceable,” it calls for stricter government involvement in setting standards for the use of electronic control vehicle systems.


The new report completes a series of studies set in motion by the National Highway Traffic Safety Administration which, in March 2010, asked both the NAS’s National Research Council, as well as NASA, to see why there were so many complaints about what the media was referring to as “runaway Toyotas.”


The problem first made headlines in the summer of 2009, when a California Highway Patrol Officer and several members of his family were killed in a fiery crash involving a Lexus they had borrowed. The maker initially recalled several million vehicles due to a problem it described as “carpet entrapment,” but in January 2010 it added millions more due to a potentially sticky accelerator linkage.


Ultimately, more than 8 million Toyota and Lexus vehicles were recalled in the U.S. alone. But the NHTSA received numerous additional complaints — with plaintiffs’ attorneys lining up to file lawsuits against the automaker — alleging some unknown electronic gremlin was also at work.


Last February, the NASA panel issued its report, contending it had found no indication of electronic defects. The National Research Council study echoes that, putting the primary blame on driver error. That had been the conclusion of other investigators in a number of instances — in one, police investigators found that a woman driver involved in a crash had been pressing on the gas pedal, rather than the brake, so hard she had bent its linkage.


Nonetheless, the latest study does not rule out electronic issues, which it cautioned can result in “untraceable faults,” with no physical evidence — other than a crash — to show when there might have been a problem such as a momentary software glitch.


“Some failures of software and other faults in electronics systems do not leave physical evidence of their occurrence, which can complicate assessment of the causes of unusual behaviors in the modern, electronics-intensive automobile,” the report cautioned.


Nonetheless, Louis Lanzerotti, the chairman of the panel and a New Jersey Institute of Technology physics professor, said during a conference call that, “All the data available to us indicated the conclusion that there was no electronic or software problem” that may have caused the Toyota unintended acceleration reports.”


The new study called for a number of steps to be taken to reduce the likelihood that electronic hardware and software do cause problems in the future – a critical issue considering the increasing use of digital technology in modern automobiles. Among the recommendations:

NHTSA should convene an advisory panel to set uniform industry testing standards for electronic systems; New vehicles should be equipped with aircraft-style black boxes to make it easier to trace and identify defects; Regulators need to continue research on pedal design and placement.

The study also called for closer cooperation between NHTSA’s researchers and the Transportation Department’s Office of Defect Investigations.


While some critics questioned the latest study — as they did earlier NHTSA and NASA findings, Transportation Secretary Ray LaHood said that in his eyes the latest report “does close the book” on the Toyota scandal.


At one point, following the second unintended acceleration recall, LaHood had said owners of Toyota vehicles involved in the recalls might think about parking those products until they were repaired.


The NHTSA ultimately levied a series of record fines against Toyota, including one for $33 million for delaying action on the sticky accelerator problem.


The maker, long known for seemingly bullet-proof quality, also recalled products in 2009, 2010 and 2011 for a variety of other issues, ranging from electronic brake issues with its Prius hybrid to excessive corrosion that could cause metal parts to fell off while driving the Sienna minivan.


As a result, Toyota had more recalls than any other maker in the U.S. market in 2009 and 2010, and with 3.5 million vehicles involved in service campaigns in 2011, came in just behind Honda, which last year recalled 3.7 million vehicles.


The long-term impact to the company’s reputation is unclear. Toyota — along with Honda — was one of only two major makers to suffer a sales decline in 2011. Analysts put most of the blame on the March earthquake and tsunami that severely limited global production for much of the year, but they also note cool consumer response to the latest update of the Toyota Camry at the same time as competitors like Ford are becoming increasingly aggressive in market segments long dominated by Toyota.


A new study by KBB.com shows that Toyota has regained its long-standing position as having the highest loyalty rate in the industry. But the maker is still heavily dependent on “conquesting” buyers from other brands. That, many analysts warn, could become more difficult in light of the hits Toyota’s reputation has taken.


Copyright 2012 The Detroit Bureau. All rights reserved.

Saturday, December 10, 2011

Volt is drivers' favorite, topping even Porsche

Volt is drivers' favorite, topping even Porsche

A Chevrolet Volt electric is shown at GM's Flint, Mich., plant. The car is wildly popular among owners.


The Chevrolet Volt extended-range electric car is the most popular among owners, topping a perennial favorite that costs twice as much, the Porsche 911, and a recent addition, the Dodge Challenger, according to an annual survey published Thursday by Consumer Reports.


The magazine was careful to specify that only the Challenger equipped with the “That thang got a Hemi innit?” V8 engine was named to the list, and not the girly-man fuel-sipping V6 version.


But I digress.  The Volt is the overall winner of the owner satisfaction survey, with the announcement coming at a time when the Volt is in the news for a less-good reason: fires in crash-tested vehicles days or weeks after the crash.  Ninety-three percent of owners surveyed said they would buy the Volt again, compared with 91 percent of 911 and Challenger buyers.


The Volt has a starting list price of $41,000, compared with $82,100 for the Porsche and about $30,000 for the Challenger.


Porsche via AP


The 2012 Porsche 911 Carrera is due out in February. The current edition of the car, which came in second in Consumer Reports' annual owner satisfaction survey, sells for $82,000 and up.


Chevy also grabbed the last spot on the list with the Aveo minicar, which would only retain 37 percent of its owners.  The Aveo has since been replaced by the Sonic (see review here), ensuring, at least, that the Aveo will not be last again next year. (See the full list here. Subscription required.)


Volt drivers are happy with their cars for a couple reasons.  Firstly, they are electric vehicle zealots, and they would be happy with an EZ-Go golf cart as long as it was fully charged.  EV zealotry even tops sports car zealotry, as seen by the Volt’s defeat of the 911, which is popular among sports car zealots despite its high price, useless back seat and thirst for fuel.


“These models reflect a larger trend we’ve seen in recent years: sporty cars and fuel-efficient cars with alternative drivetrains tend to generate more enthusiasm and loyalty than most other types of vehicles,” said Rik Paul, Consumer Reports automotive editor.


The second reason for Volt owners’ satisfaction is the dedicated manservant Volt adviser issued by Chevrolet who talks with owners daily about the Volt’s awesomeness.   “From the very beginning we’ve tried to provide an extraordinary customer experience to go with the technology,” said GM spokesman Greg Martin.


The combination of engaged owners and continuous discussion between GM and Volt owners has stemmed any rush to the exits even since the reports of post-crash-test fires.  For the record, these fires took place days or weeks after extreme crash testing in which the Volt successfully protected occupants and earned the highest possible safety scores.


Following the tests, the cars’ batteries were left fully charged, and because the car were also rolled over and because the battery coolant system was damaged in the tests, coolant leaked onto the charged batteries and eventually sparked fires.


The lesson here is to get out of a crashed car within a few days, and be sure to turn off the lights when exiting.  A gasoline car might not be as obliging in providing an opportunity to climb out before combusting.


Despite recent safety concerns about the Chevy Volt's battery, the popularity of electric cars is picking up traction, with CNBC's Phil LeBeau.


In the real world, “five or six” Volts have been totaled in severe crashes, with no fires resulting, Martin said.


To mollify any potential concerns while GM undertakes its investigation into how best to prevent post-crash fires, the company is offering a free loaner car to Volt owners who prefer to park their electric car for now. GM CEO Daniel Akerson even has offered to buy back the Volts of anyone who is concerned about the fire hazard, according to The Associated Press.


The number of drivers asking for a loaner car is “a handful,” according to Martin.  Hmm, that’s suspiciously similar to the number who have already crashed their cars.  Is anyone checking to see if the people asking for loaners have already totaled their Volt?

Monday, December 5, 2011

Drivers still want electric cars, Nissan says

nissan-leaf

Muhammad Hamed / Reuters


The Nissan Leaf, an electric car, is shown.


By Dan Carney


Demand for electric cars remains steady, even in the face of slightly lower gas prices.


That’s the view put forward by Nissan. The automaker says it is seeing unrelenting demand for its limited-production Leaf electric vehicle continuing for the foreseeable future, in spite of rumors that consumer fascination with battery-powered cars is waning.


Through Oct. 31, Nissan sold 8,048 of its electric cars, giving the companies a bit of insight into the car’s appeal to customers.


Thanks to data from the Leaf’s OnStar-like telematics system, owner surveys and direct discussions with enthusiastic owners, Nissan has learned that the little battery-powered Leaf is shouldering most of the transportation chores for its owners.


Brendan Jones, director of electric vehicle marketing and sales strategy at Nissan, reports that owners say that the car they bought as a second car is actually being used by drivers as their family’s number one vehicle.


“They drive it primarily because it is fun to drive,” he said, but of course they wouldn’t have that option if the car’s driving range proved to be too short for practical use.


It turns out that owners drive about 35 miles a day, the same distance as most surveys of American drivers report as the average distance for U.S. drivers. But drivers often overestimate their own daily mileage, and this makes them wary of a car that has a cold-weather driving range of as little as 65 miles.


The “range anxiety” of being stranded with a dead battery is overblown, asserted Jones. 


“Range anxiety is dead,” he stated, insisting that the real issue is driver unfamiliarity with something new. “That newness needs to be overcome with information.”


Nissan Leaf drivers are typically making three trips between recharges, so they aren’t usually in the situation of having to make a beeline directly from one plug to the next for fear of being stranded.


However, Nissan is also reducing the impact of actually getting stranded, so that it won’t be the ordeal it is today, when the car has to be towed in from the road. Nissan provides Leaf owners with free roadside assistance, and the company is adding mobile quick chargers to the response trucks, so that they can provide the equivalent of a can of gas to get a Leaf with a dead battery pack back on the road.


Customers have embraced the optional fast-charging port, which enables specialized commercial-grade chargers to quick-charge the Leaf to 80 percent capacity in just 30 minutes. Enough customers were choosing that $700 option, despite a current shortage of suitable charging stations, that Nissan decided to make the quick-charging port standard equipment on the $940 uplevel SL trim package, Jones reported. There are currently 562 such quick chargers being installed nationwide, he added.


Nissan is continuing its nationwide rollout of Leaf availability, and the company anticipated delivering another 10,000 of the cars to consumers in 2012. Once Nissan’s Leaf battery plant opens in Smyrna, Tenn., the company will have the capacity to deliver 150,000 Leafs per year.


But Jones says that Nissan is not concerned about potential difficulty finding that many customers for battery cars.


“The competition isn’t pulling out of the [electric vehicle] market,” he pointed out. “The competition is coming into the market.” That demonstrates industry-wide confidence that customers will embrace electric cars, he added.


One interesting purchasing characteristic of Leaf drivers is that a surprising number of them are choosing to buy their cars outright. Nissan had predicted that most buyers would lease their Leaf as a way to make its acquisition more affordable, and as a hedge against concerns about battery longevity and the possibility of a pricey battery replacement in the future.


But instead, the majority of Leaf customers bought their cars, most of them either paying cash or paying for the car with outside financing. Jones hypothesized that perhaps some EV enthusiasts were worried about General Motors’ decision to withdraw its EV1 electric car fleet at the end of the cars’ leases, so they bought them outright to ensure they could keep the cars.


Today 40 percent of Leaf customers are buying the cars with cash or outside financing. But Nissan expects as the Leaf pushes into the Northeastern states, that customers there who are more familiar with leasing luxury cars will be more prone to leasing their Leafs.


Or maybe they just aren’t worried anymore about their cars going to the crusher when the lease is up.

Wednesday, September 28, 2011

What, not your town? D.C. has worst drivers

AppId is over the quota AppId is over the quota According to a recent report issued by Allstate Insurance Co., Washington, D.C. can lay claim to having the worst — or at least the most accident-prone — drivers among the 200 largest cities in the U.S.


Residents of our nation’s capitol were found to get into collisions on average once every 4.8 years. This means they’re 107.3 percent more likely to get into an accident every time they take the wheel than the typical driver in the U.S., who wrecks his or her car once every 10 years.


Other cities ranking high on the list include such traffic hot spots as Baltimore, Md., Glendale, Calif., Newark, N.J., Providence, R.I., and Philadelphia, Pa. Los Angeles holds down the number 11 position, with the driving population crashing their vehicles once every 6.6 years. Surprisingly, New York City didn’t place among the top 10, being ranked at number 20 in the survey, with motorists getting into collisions on average once every 7.3 years (guess cab drivers weren’t counted as part of the study).


While collisions have been on the decline, fatalities from car crashes still claim over 32,000 lives each year. “Human behavior is the biggest cause of accidents. It is vital for us to educate American drivers about safe driving behaviors they can demonstrate on the road that will help make our roadways safer,” says Mike Roche, executive vice president for Allstate’s claim organization.


The Northbrook, Ill.-based insurer found the safest drivers residing in smaller cities — motorists living in U.S. cities with populations of over one million are more likely than the national average to get into accidents. Allstate says the safest drivers can be found in Fort Collins, Colo., where the average motorist experiences an auto collision only once every 14 years. Other cities on the safest driver list included Boise, Idaho, Lincoln, Neb., Chandler, Ariz., and Huntsville, Ala.


The study was based on property damage claims reported over a two-year period (from January 2008 to December 2009) adjusted for population, with a weighted average of the two-year numbers used to determine the results.


© 2011 Forbes.com

Monday, September 12, 2011

What, not your city? D.C. has the worst drivers

According to a recent report issued by Allstate Insurance Co., Washington, D.C. entitled can - set for the worst, or at least the most driver - driver among the 200 largest cities in the United States

Found in collision on average every 4.8 years receive people of our nation Capitol. That means, are more likely to get in an accident, every time when the steering wheel as the typical driver in the United States to take, his or her once every 10 years applied 107.3%.


Other cities, ranking high on the list are such traffic hotspots as Baltimore, MD, Glendale, California, Newark, n.j., Providence, r.i., and Philadelphia, PA. Los Angeles holds the position as the number 11, with people driving their vehicles crashing every 6.6 years. Surprisingly place not New York City in the top 10, reached spot at number 20 in the poll with driver, always in collisions on average every 7.3 years (guess taxi drivers were counted as part of the study).


During collisions on the retreat, victims of road accidents claim, yet every year more than 32,000 lives. "Human behaviour is the most common cause of accidents." It is important for us to educate us drivers about safe driving behaviours that they can prove on the road towards that helps "Our streets safer, says Mike Roche, executive Vice President of Allstates claim organization."


Northbrook, Illinois-based insurer here in smaller towns - motorists, who are living in cities of the United States with a population of more than one million more than the national average for accidents to get found the safest drivers. Allstate says the safest drivers in Fort Collins, Colorado, can be found, where the average driver a car collision only once every 14 years of experience. Other cities in the safest driver list contain, Boise, Idaho, Lincoln, Neb., Chandler, Arizona, and Huntsville, Ala.


The study is based on property damage claims population reported adjusted over a two year period (from January 2008 to December 2009), a weighted average of the two-year numbers used to determine the results.


© 2011 Forbes.com